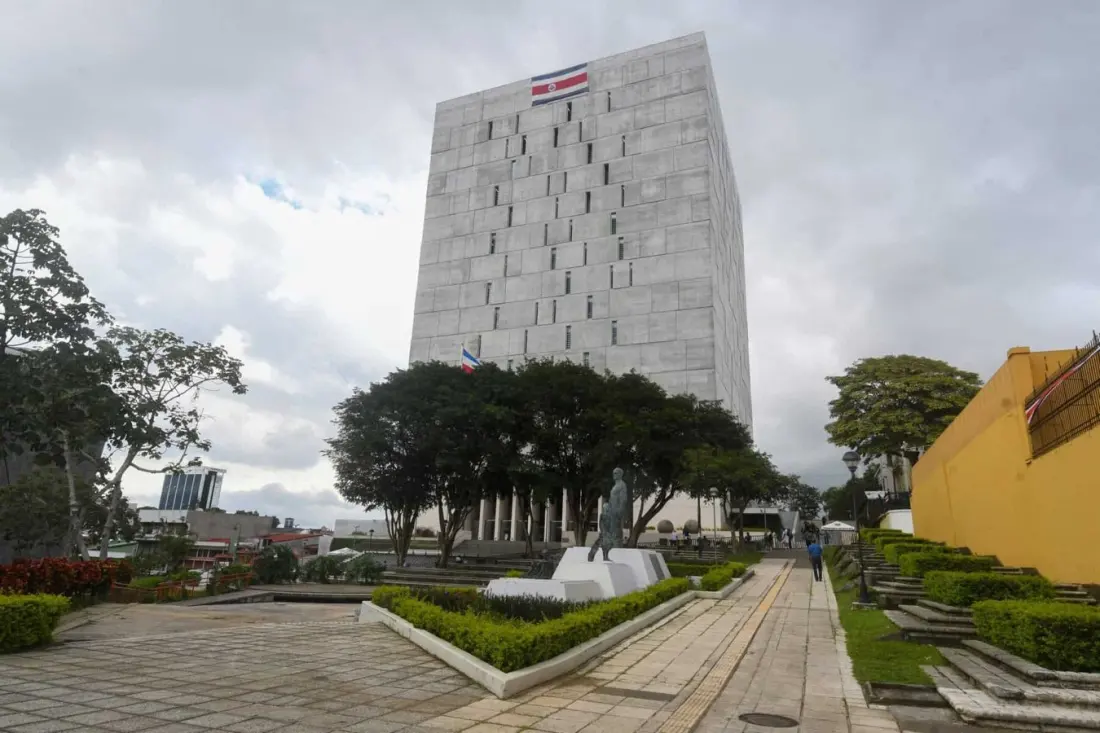
Costa Rica has long been a magnet for retirees, remote workers and investors thanks to one big draw: a territorial tax system that generally leaves your overseas income alone. That could be about to change. A new bill presented to the Legislative Assembly proposes a 15% tax on certain passive income earned abroad by Costa Rican tax residents.
The draft law targets five categories of foreign income: interest, dividends, royalties, rental income and capital gains. If someone who is a Costa Rican tax resident collects rent on a flat in Madrid, dividends from a US brokerage account, or profits from selling assets overseas, those earnings could fall within scope. Crucially, this is not a blanket tax on every dollar arriving from abroad — salaries, pensions and retirement income are not automatically captured, though how each income stream is classified under tax law will matter.
The bill marks a real shift. Costa Rica has historically taxed only income generated inside the country. A 2023 reform, prompted by concerns from the European Union, extended taxation of foreign passive income only to specific multinational company scenarios. The new proposal goes much further, using tax residency as the main test and potentially sweeping in individuals, companies, trusts and investment funds based in Costa Rica that hold income-producing assets abroad.
There is some protection against double taxation: if tax has already been paid or withheld in another country — say, US withholding on dividends — that can be credited against the Costa Rican calculation. The government's argument is fairness, closing the gap between people earning investment income locally and those earning it from assets abroad.
The key caveat: nothing has changed yet. The bill must pass through the Legislative Assembly, where it can be amended or rejected entirely. It was introduced alongside a separate measure that would overhaul tax exemptions and scrap some existing ones.
Why should travellers care? Anyone dreaming of retiring on the Pacific coast, running a rental villa back home while living in the Central Valley, or building a long-term base in Costa Rica should watch this closely. Immigration residency and tax residency are not the same thing — and if you plan to become a tax resident, the treatment of your foreign dividends, rents and gains could look very different after this law passes. For now, the smart move is to stay informed and get local tax advice before assuming your overseas income will stay untaxed.